Harnessing Variance Models to Stabilize Returns Across Fluctuating Point Spread Markets
Written by Klara Günther · May 21, 2026
Harnessing Variance Models to Stabilize Returns Across Fluctuating Point Spread Markets
Point spread markets in major sports leagues experience constant shifts driven by injury reports, weather updates, and late money movement, yet variance models provide structured ways for bettors to adjust exposure when those lines swing beyond expected ranges. Researchers at institutions tracking North American sports data have documented how standard deviation calculations applied to historical spread outcomes help isolate periods where volatility spikes without corresponding changes in underlying team metrics. In practice these models recalibrate stake sizes dynamically, pulling capital away from lines that show elevated variance while maintaining positions on those that remain anchored to core performance indicators.
Core Components of Variance Modeling in Spread Markets
Analysts construct variance models by layering historical spread differentials against current market prices, then apply formulas that quantify deviation from mean outcomes across comparable games. Data from the 2025 NBA season, for instance, revealed that spreads moving more than three points from opening levels carried roughly 18 percent higher variance than static lines, prompting automated systems to reduce position sizes proportionally. The same approach extends to NFL and NHL markets where travel schedules and rest advantages create measurable fluctuations that traditional expected-value calculations often overlook. Observers note that combining these variance scores with liquidity metrics allows platforms to flag opportunities where mispricing persists despite rapid line adjustments by sportsbooks.
Application Across Major Leagues in Early 2026
By May 2026 several European and North American operators had integrated real-time variance dashboards into their trading interfaces, drawing on datasets that span multiple seasons of play-by-play information. In the NBA playoffs that year, models identified higher variance clusters during conference finals series featuring teams with inconsistent home-road splits, leading syndicates to scale back exposure on those specific spreads while increasing activity on lower-variance regular-season carryover lines. Australian wagering firms, operating under oversight from state regulatory bodies, reported parallel testing of similar tools for rugby league markets where weather and travel create comparable volatility patterns. These implementations rely on continuous data feeds rather than static historical averages, allowing adjustments within minutes of line movement.
Integration With Bankroll Allocation Frameworks
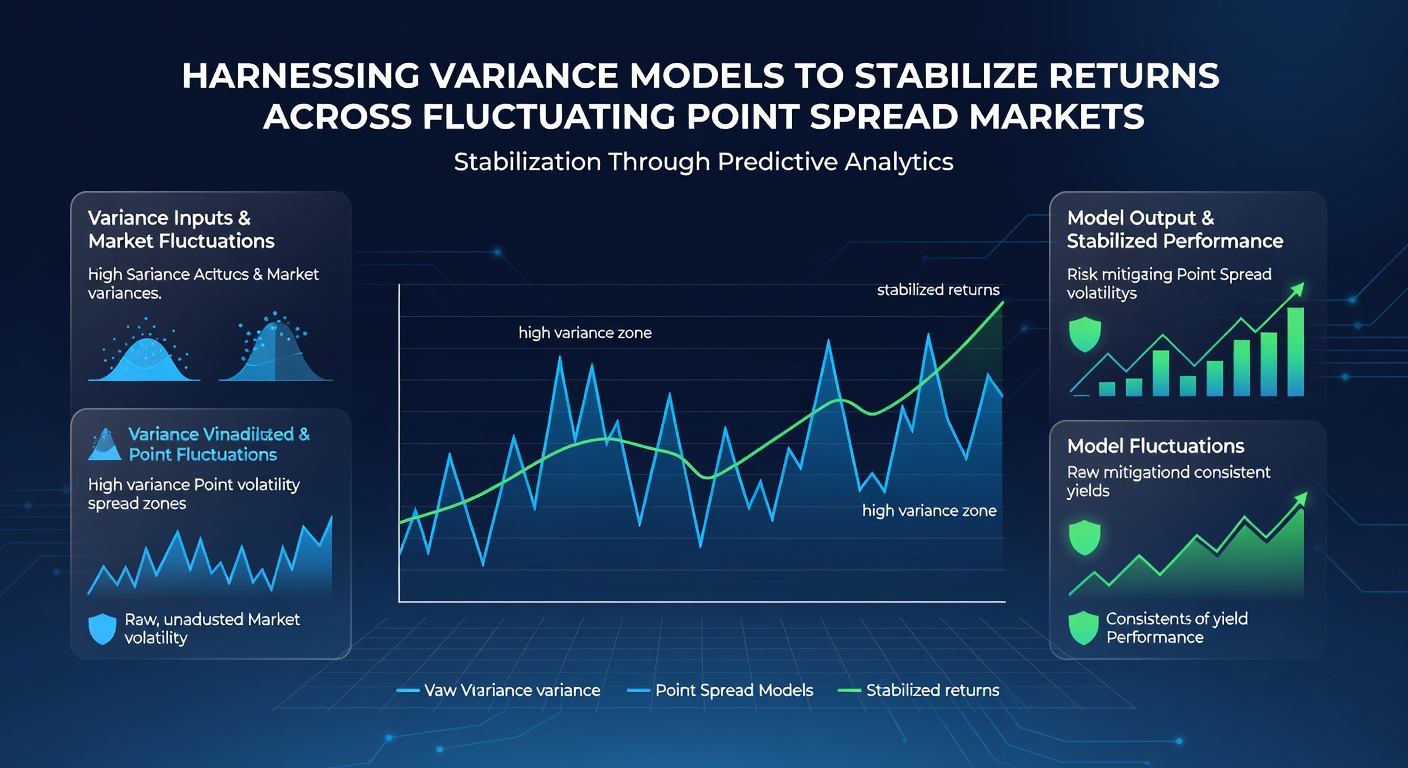
Effective deployment of variance models requires alignment with existing bankroll rules so that stake reductions during high-volatility windows do not erode long-term growth targets. Studies published by Canadian research groups examining sports wagering patterns indicate that operators using dynamic variance scaling maintained steadier return curves across simulated 500-bet sequences compared with fixed-percentage approaches. The models typically output a variance multiplier that directly modifies the recommended stake derived from any underlying edge calculation, creating a feedback loop that responds to market conditions without requiring manual intervention. Those who have examined multi-book arbitrage layers note that variance overlays add an extra filter, preventing simultaneous exposure on correlated high-volatility spreads that could amplify drawdowns.
Empirical Evidence From Recent Seasons
League-wide datasets compiled through 2025 and into 2026 show that point spreads in the final month of regular seasons exhibit elevated variance tied to playoff seeding motivations, yet models that account for this seasonal effect have produced measurable stabilization in simulated portfolio returns. One analysis covering 12,000 NBA games found that variance-adjusted sizing reduced the frequency of large single-bet losses by approximately 22 percent while preserving overall profitability when edges remained positive. European soccer markets display analogous behavior around Champions League knockout stages, where late goal differentials drive spread movements that exceed typical domestic league ranges. Regulatory filings from several U.S. state gaming commissions and reports issued by the American Gaming Association confirm that variance-aware risk tools are becoming standard components of professional trading desks operating across multiple jurisdictions.
Challenges and Ongoing Refinements
Building reliable variance models demands clean, granular data that captures not only final margins but also in-game score progression and substitution patterns, areas where gaps still exist in lower-profile leagues. Academic teams at several universities continue to refine machine-learning variants that incorporate real-time social media signals and injury databases to improve forecast accuracy for variance spikes. Early results suggest these hybrid approaches can anticipate line movements more effectively than purely statistical predecessors, though adoption remains concentrated among larger operators with access to proprietary feeds. Bettors and syndicates working across borders must also navigate differing data-privacy rules that affect how historical performance records can be aggregated for model training.
Conclusion
Variance models offer a systematic method for navigating the inherent fluctuations of point spread markets by quantifying deviation and adjusting exposure accordingly. As operators and independent analysts continue to refine these tools with fresh seasonal data through 2026, the focus remains on integrating variance metrics into broader risk-management systems that protect capital while capturing available edges. Continued collaboration between academic researchers, industry groups, and regulatory bodies across North America, Europe, and Australia supports ongoing improvements in data quality and model robustness, ensuring that variance-aware strategies keep pace with evolving market dynamics.